Buying a home in October can be an exciting opportunity, especially if you want to settle into your new place before the holidays. But if your goal is to close before the end of the year, timing matters. From securing mortgage approval to scheduling inspections and navigating the final paperwork, every step plays a role in keeping your home purchase on track.
For homebuyers in Richmond, Virginia, and surrounding communities like Midlothian, Short Pump, Bon Air, and Henrico County, October is an excellent time to get organized and make strategic decisions. The fall real estate market brings its own advantages, but it also means you need to pay attention to deadlines, lender requirements, and holiday schedules.
The good news? With the right preparation and a knowledgeable local real estate professional, you can move toward closing day with greater confidence and fewer surprises.
Whether you're purchasing your first home, upgrading to a larger property, or relocating to Central Virginia, here's how to prepare for a smooth year-end real estate closing.

1. Get Your Mortgage Financing Ready Before You Start House Hunting
If you're hoping to close on a home before December 31, one of the smartest moves you can make in October is to get your financing in order.
Mortgage approval involves more than submitting an application and waiting for a decision. Your lender will review your income, credit history, existing debts, employment information, assets, and other financial details. Getting ahead of these requirements can help prevent avoidable delays later.
Get Pre-Approved, Not Just Prequalified
Mortgage prequalification can provide an initial estimate of what you may be able to borrow. A mortgage pre-approval generally involves a more detailed review of your financial information and can help demonstrate to sellers that you're a serious buyer.
Before touring homes in Richmond, Chesterfield County, or Henrico County, connect with a mortgage lender to understand your budget, estimated monthly payment, down payment requirements, and potential closing costs.
Remember that your purchase price isn't the only number that matters. Property taxes, homeowners insurance, mortgage insurance when applicable, utilities, and maintenance expenses can all affect your monthly housing budget.
Keep Your Finances Consistent
Once you're working toward mortgage approval, avoid making major financial changes without discussing them with your lender.
For example, consider holding off on opening new credit cards, financing a vehicle, or making large purchases that could affect your debt-to-income ratio or available cash reserves. Avoid changing jobs or moving significant sums of money between accounts without first understanding the potential impact on your loan.
Your lender may request updated bank statements, pay stubs, tax documents, or explanations of certain deposits. Responding promptly can help keep the underwriting process moving.
October tip: Ask your lender what documentation you should prepare now and which deadlines are most important for a closing before the holidays.

2. Build a Realistic Homebuying Timeline Around Year-End Deadlines
Finding a home in October and closing before the end of December may be achievable, but the timeline depends on several moving parts.
Your purchase contract, financing, inspection results, appraisal, title work, and closing arrangements all need to come together. A delay in one area can affect the rest of the transaction.
That's why buyers should create a realistic timeline early rather than assuming everything will fall into place automatically.
Understand the Major Milestones
While every transaction is different, a typical financed home purchase includes several key stages:
October: Confirm financing, identify your preferred neighborhoods, tour homes, and submit an offer when you find the right property.
After contract ratification: Complete inspections and other agreed-upon due diligence within the deadlines specified in your contract.
During underwriting: Provide requested documents, arrange the appraisal, and address lender conditions.
Before closing: Review the title and settlement information, obtain homeowners insurance, complete any required final documentation, and confirm your closing arrangements.
Closing day: Complete the required signing and funding steps, satisfy applicable contract and lender requirements, and receive the keys when possession is authorized.
These are planning guidelines, not guaranteed deadlines. Some purchases move faster, while others take longer because of appraisal issues, repairs, financing complications, or title concerns.
Plan Around Thanksgiving and Christmas
Late November and December can bring additional scheduling challenges. Lenders, appraisers, settlement providers, inspectors, and other professionals may have reduced availability around holidays.
If you're purchasing a home in the Museum District, Manchester, or Short Pump, communicate your desired closing date to your REALTOR® and lender as early as possible.
Ask which milestones must be completed before holiday closures and whether your preferred closing date leaves enough time to resolve unexpected issues.
Also, remember that closing before December 31 is not entirely within your control. The seller's circumstances, lender processing, and third-party requirements can all affect the final date.
October tip: Set a target closing date with some breathing room. A little flexibility can make a significant difference when an unexpected document or scheduling issue arises.
3. Choose the Right Neighborhood and Move Quickly When the Right Home Appears
October buyers often have a clearer sense of their priorities than they did when they first started searching. You may know how many bedrooms you need, which commute works best, or whether you want to be near schools, parks, restaurants, or shopping.
Use that clarity to make your home search more focused.
Central Virginia offers a wide range of lifestyles, from established city neighborhoods to suburban communities and properties with more room to spread out.
Explore Richmond and the Surrounding Communities
Consider what matters most to your household before narrowing your search.
Short Pump: Explore established neighborhoods, shopping, dining, and convenient access to major roadways.
Midlothian: Consider suburban communities, parks, shopping areas, and commuting options throughout Chesterfield County.
Bon Air: Look into established residential streets, mature trees, and convenient access to Richmond and surrounding communities.
Museum District: Explore historic architecture, walkable streets, and proximity to museums, restaurants, and city amenities.
Manchester: Consider urban living, riverfront access, and the area's evolving residential and commercial landscape.
Henrico County: Compare different communities, housing styles, commute routes, and access to everyday services.
As you compare locations, look beyond the listing photos. Visit the neighborhood at different times of day, test your commute, review available services, and consider the property's ongoing costs.
If you're purchasing in a homeowners association, review applicable fees, rules, and documents. If you're considering an older home, pay particular attention to maintenance needs and potential repair expenses.
Stay Focused on Your Must-Haves
A year-end closing goal can create pressure to choose a home quickly. However, rushing into the wrong property can lead to more significant problems than waiting for the right fit.
Separate your essential requirements from your preferences. Your must-haves might include a certain number of bedrooms, a workable commute, or an accessible layout. Features such as a specific paint color or a particular kitchen finish may be easier to change later.
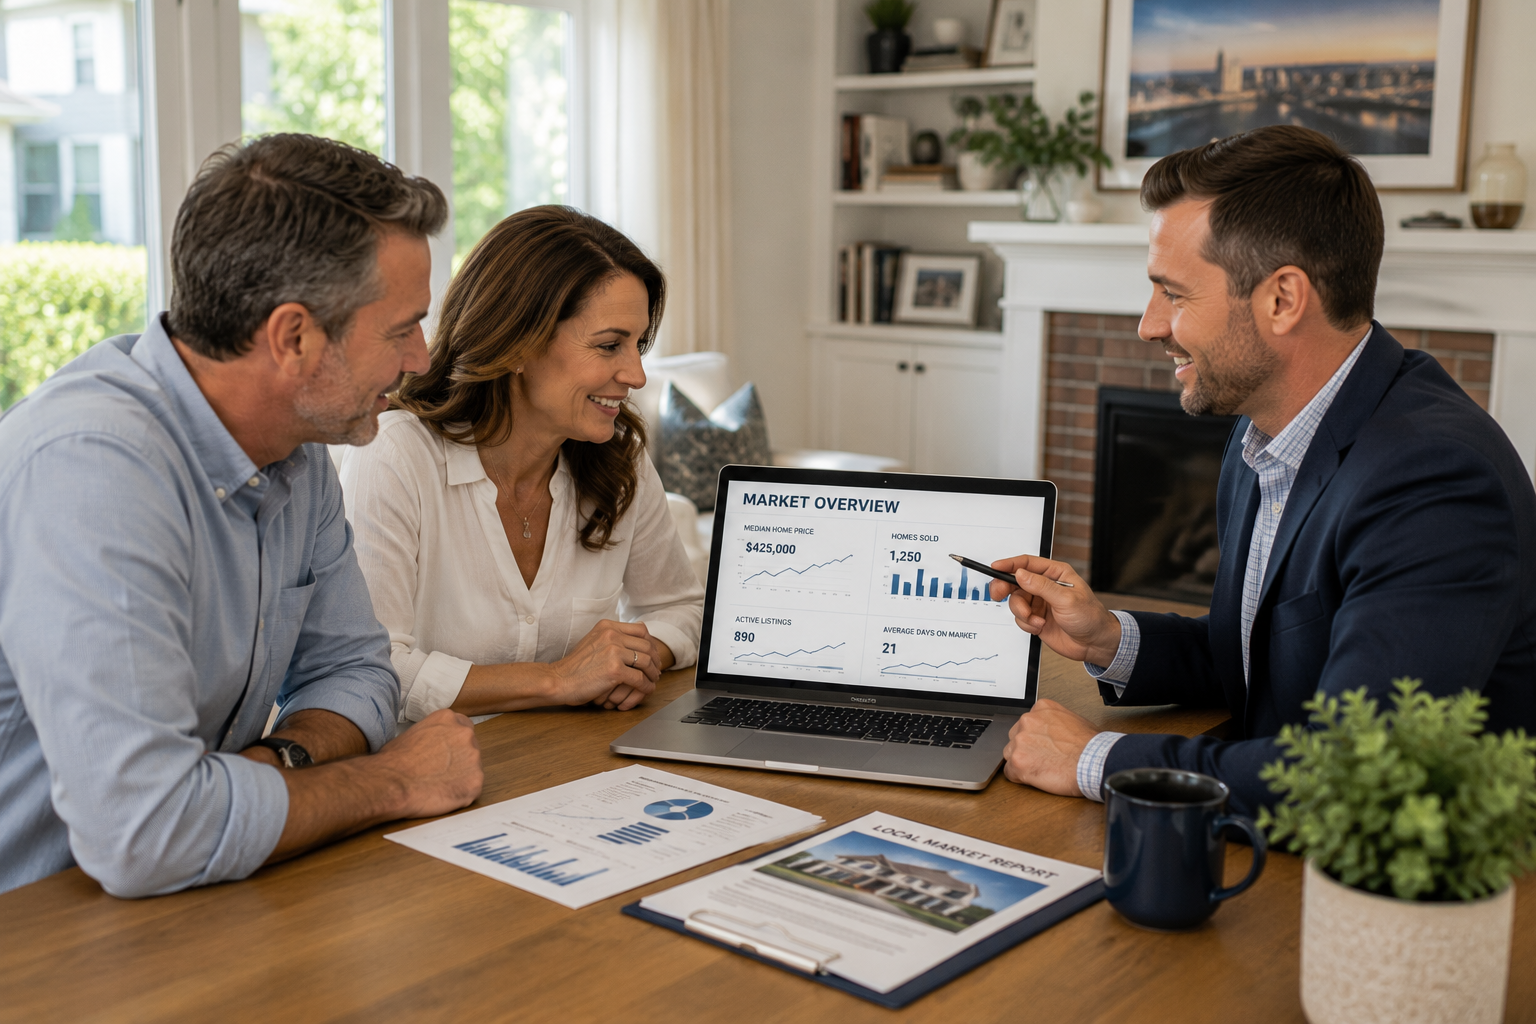
When a promising property becomes available, work with your REALTOR® to evaluate comparable sales, the home's condition, and the offer terms before deciding how to proceed.
October tip: Prepare your decision-making criteria before touring homes. You'll be better positioned to act confidently without overlooking important details.

4. Schedule Inspections, Appraisals, and Insurance Early
Once your offer is accepted, the process shifts from finding a home to completing the steps required to reach closing.
This is where organization becomes especially important.
Inspections, appraisals, insurance arrangements, and title work can involve separate professionals and schedules. Coordinating them early gives you more time to address problems before your planned closing date.
Don't Overlook the Home Inspection
A home inspection can help you better understand the property's condition, including potential concerns involving the roof, plumbing, electrical systems, heating and cooling equipment, and other accessible components.
Read your purchase contract carefully and follow the applicable inspection deadlines. Depending on the agreement, you may have options to negotiate repairs, request other remedies, or reconsider the transaction under specified conditions.
For older homes in Richmond's Museum District or established neighborhoods in Bon Air, ask your inspector about age-related maintenance concerns and whether further evaluation by a qualified specialist is warranted.
An inspection is not a guarantee against future repairs, but it can help you make a more informed decision.
Understand the Appraisal Process
If you're using a mortgage, your lender will generally require an appraisal to evaluate the property's value for lending purposes.
An appraisal that comes in below the contract price can create additional decisions for the buyer and seller. Depending on the contract and financing terms, possible paths forward may include renegotiation, bringing additional funds to closing, or pursuing another option available under the agreement.
Ask your lender and REALTOR® what could happen if the appraisal differs from the purchase price.
Arrange Homeowners Insurance in Advance
Your lender may require proof of homeowners insurance before closing. Start comparing coverage options early, and provide your insurer with accurate information about the property.
Premiums and availability can vary based on the home's age, roof condition, location, coverage limits, deductible, and other underwriting factors.
If the property is older or has features that require additional review, an early insurance quote can help identify potential concerns before closing approaches.
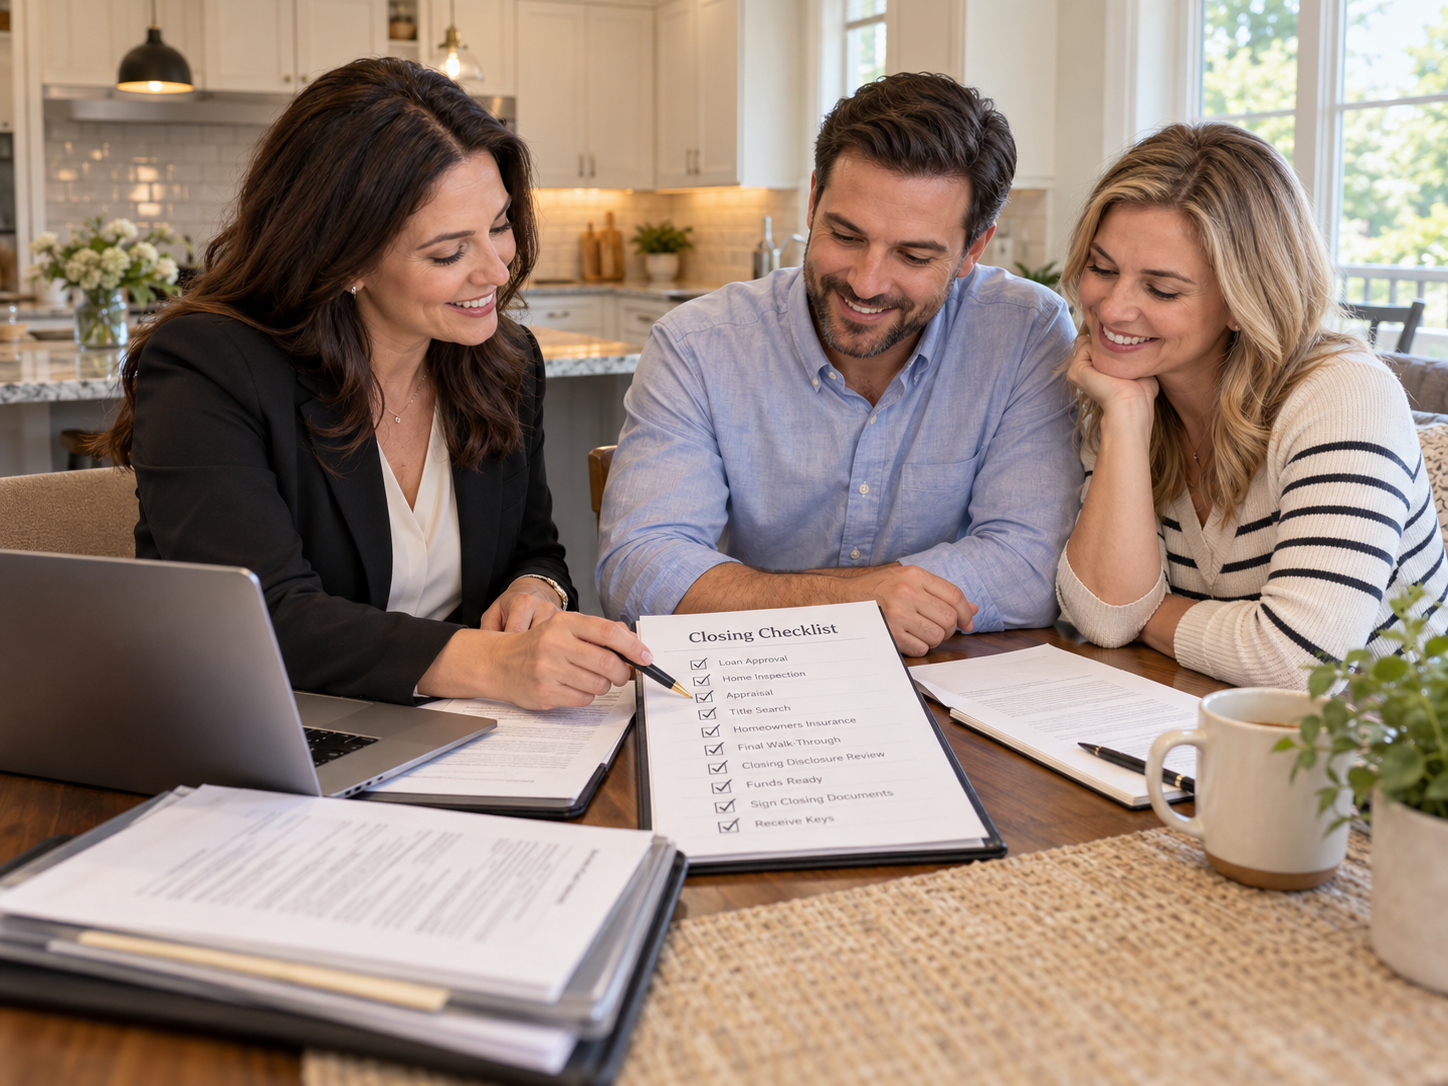
October tip: Keep a shared checklist of appointments, documents, deadlines, and outstanding questions. Confirm each milestone rather than assuming it has been completed.

5. Prepare for Closing Costs, Final Walk-Throughs, and Last-Minute Requests
A successful home purchase involves more than getting loan approval. You also need to prepare for the financial and logistical details of closing.
Understanding these responsibilities ahead of time can reduce stress during the final weeks of your transaction.
Review Your Closing Costs Early
Closing costs may include lender fees, appraisal charges, title and settlement services, recording fees, prepaid property taxes, homeowners insurance, and other transaction-related expenses.
The exact amounts depend on your loan, contract, location, and other factors.
Your lender should provide a Loan Estimate early in the mortgage process. Before closing, you'll generally receive a Closing Disclosure that outlines the final loan terms and closing costs. For most covered mortgage transactions, the Closing Disclosure must be received at least three business days before closing.
Review the documents carefully. If a charge looks unfamiliar or the figures differ from what you expected, ask your lender or settlement provider for clarification.
Also, verify wiring instructions directly with your trusted settlement provider using a previously verified phone number. Real estate transactions can be targets for wire fraud, and last-minute email instructions should never be accepted without independent verification.
Complete Your Final Walk-Through
Your final walk-through is an opportunity to confirm that the property is in the expected condition and that agreed-upon repairs or other contractual obligations have been addressed as applicable.
Check the major areas of the home, verify that agreed-upon items remain, and look for any obvious changes since your last visit.
If you identify a concern, contact your REALTOR® promptly so the appropriate parties can discuss it before closing.
Keep Your Moving Plans Flexible
If you're moving before the holidays, book movers early and avoid scheduling every part of the move around an unconfirmed closing date.
Prepare a moving checklist that includes utility transfers, address changes, internet installation, packing, and arrangements for children or pets.
If you're relocating to Richmond from another part of Virginia or out of state, consider how holiday travel and seasonal weather could affect your plans.
Finally, avoid assuming that signing documents automatically means you can move in immediately. Confirm funding, recording where applicable, and the contractual possession terms with your settlement provider and REALTOR® before arranging access.
6. Work With a Local REALTOR® to Keep Your Year-End Purchase on Track
Even organized buyers can encounter unexpected challenges. A seller may need additional time, an appraisal may require follow-up, or a lender may request another document before issuing final approval.
Having a local real estate professional to help coordinate communication and explain your options can make the process easier to navigate.
A REALTOR® familiar with Richmond, Chesterfield County, Henrico County, and the broader Central Virginia real estate market can help you evaluate properties, understand contract deadlines, communicate with the other parties, and stay focused on the steps ahead.
Local knowledge also matters when comparing neighborhoods, reviewing comparable sales, and identifying questions to ask about a property's condition or location.
Your agent cannot control every lender, inspection, title, or settlement deadline. However, clear communication and proactive planning can help you identify potential issues earlier and respond more effectively.
Your October Year-End Closing Checklist
Before moving forward, make sure you've addressed these key items:
Obtain mortgage pre-approval and understand your budget.
Gather financial documents and respond promptly to lender requests.
Identify target neighborhoods and define your must-have features.
Discuss your desired closing date with your REALTOR® and lender.
Track contract deadlines for inspections, financing, and other contingencies.
Schedule inspections and coordinate appraisal requirements.
Compare homeowners insurance options.
Review estimated closing costs and maintain sufficient available funds.
Confirm the Closing Disclosure and secure closing arrangements.
Verify wire instructions independently and prepare for the final walk-through.
Keep moving plans flexible until closing and possession are confirmed.
Make Your Year-End Homebuying Goals Happen With The Wilson Group
October can be a productive time to buy a home in Richmond, VA, but reaching the closing table before the end of the year takes preparation, communication, and a realistic plan.
By organizing your financing, understanding your contract deadlines, scheduling inspections early, and preparing for closing costs, you can put yourself in a stronger position to navigate the process.
Whether you're searching for a home in Short Pump, exploring Midlothian neighborhoods, considering a property in Henrico County, or looking for a home closer to Richmond's Museum District or Manchester, local guidance can help you make informed decisions.
The Wilson Group is here to help buyers navigate the Central Virginia real estate market with personalized guidance and a clear understanding of the homebuying process.
Ready to find your next home and work toward a smooth year-end closing? Connect with The Wilson Group to discuss your goals, explore available homes, and create a buying strategy that fits your timeline.
Visit The Wilson Group Page to get started. Your next chapter in Central Virginia could be closer than you think.